Global fossil fuel emissions are on course to decline this year for the first time outside a recession or a pandemic. The cause is a Gulf conflict that has destroyed oil demand, rather than the effect of climate policy.
Global fossil fuel emissions are set to fall by about 0.5% in 2026, according to analysis by Carbon Brief’s Dr Simon Evans. The estimate is built on three International Energy Agency forecasts for coal, oil and gas.
The contrast with recent years is evident. The Global Carbon Budget put 2025 fossil CO2 at a record 38.1 billion tonnes, 1.1% above 2024. Emissions last fell in 2020, when they dropped 7% as the pandemic grounded the world economy. Before that, the 2009 financial crisis produced a fall of 1.3%.
What Is Driving the Fall?
The IEA’s Oil Market Report of 11 September forecasts world oil demand to decline by 2.5 million barrels a day in 2026. That is a cut of roughly 940,000 barrels a day on the agency’s estimate a month earlier.
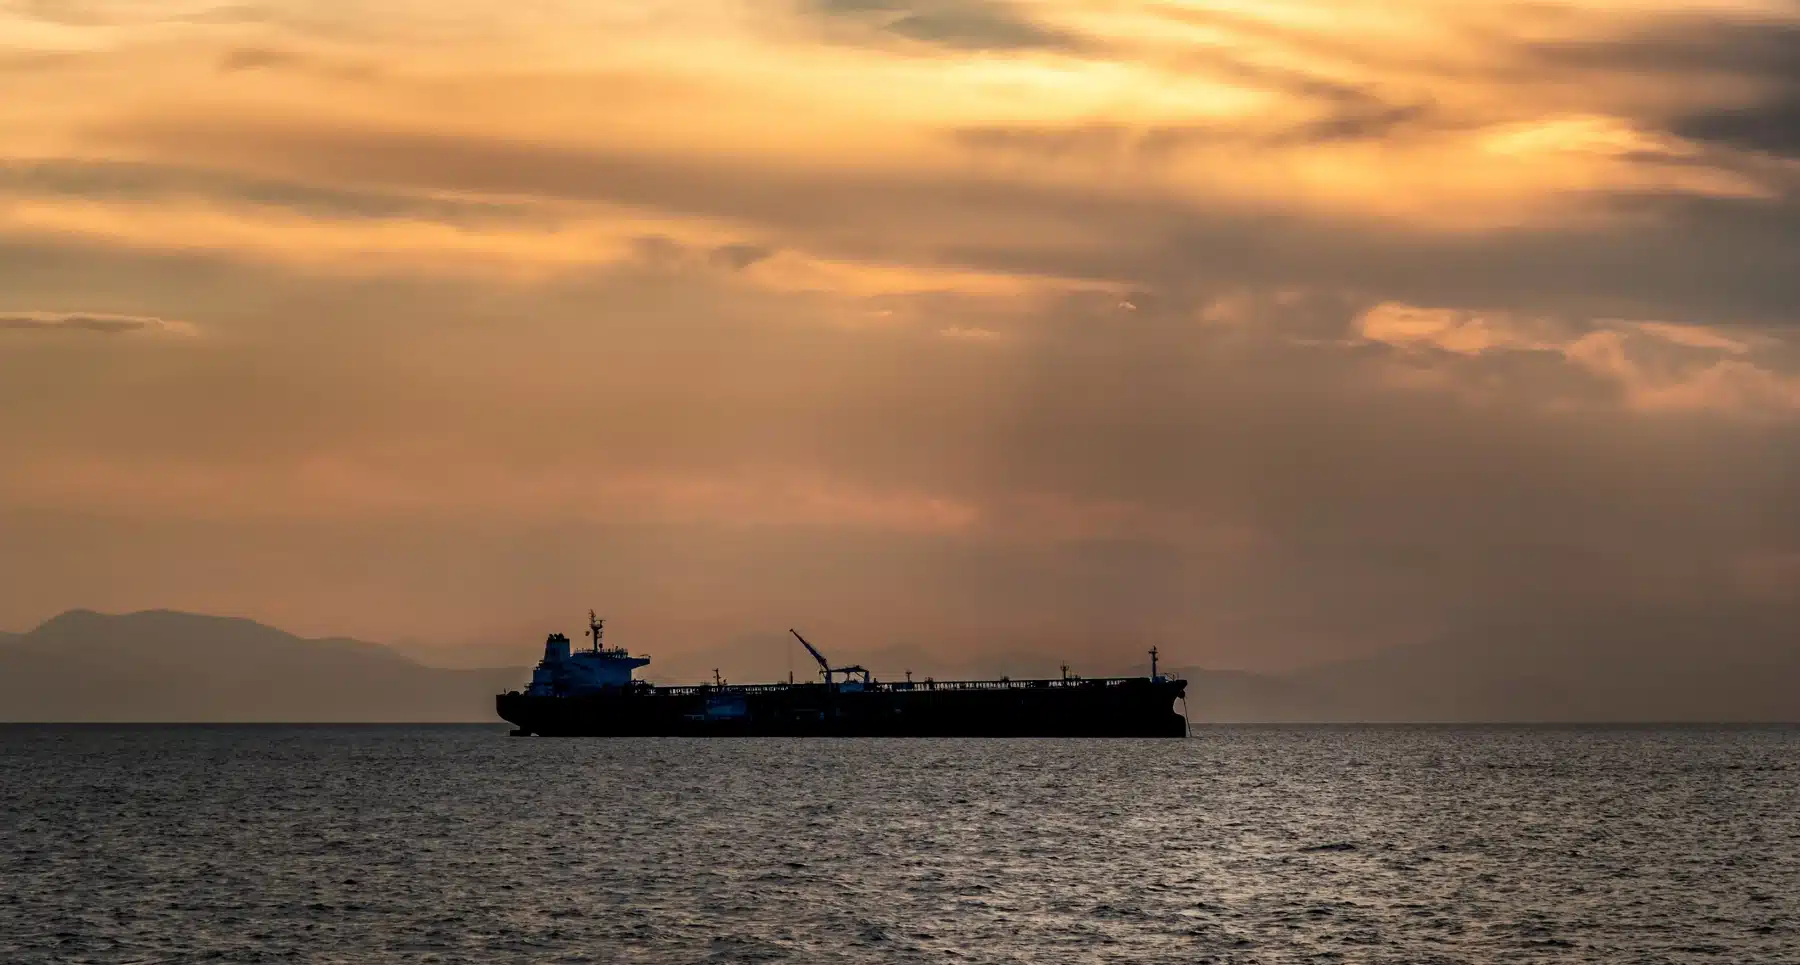
Behind the number sits the war that began in late February and the closure of the Strait of Hormuz. The IEA records total oil exports from Gulf countries at around 13 million barrels a day in August, close to half their pre-war level. Gulf net exports of diesel and gasoil averaged 390,000 barrels a day, just over a quarter of what they were before the conflict.
Carbon Brief puts oil demand down 2.4% across the year and gas demand down 0.6%. Fuel that doesn’t get delivered doesn’t get burnt.
Does Rising Coal Use Cancel It Out?
Coal demand is forecast to rise 1.2% in 2026 as buyers reach for the cheaper fuel. Carbon Brief finds the additional coal emissions are more than offset by the declines in oil and gas.
Two limits explain why. Few countries can switch from gas to coal at large scale, so substitution is capped by infrastructure rather than price. Strong El Niño conditions and curtailed renewable output in China account for part of the rest. The IEA notes that the 2027 outlooks for coal and gas depend on each other, which makes any single-year reading provisional.
What Happens When the Strait Reopens?
This is the question the forecast can’t answer. Brent crude has swung from about $118 in mid-March to roughly $70 by early July, then back to $109 in early September after renewed attacks on shipping and energy infrastructure. Demand suppressed by price returns when the price falls.
Some of it may not. “For every month the conflict lasts, the probability of permanent [oil] demand destruction increases,” said Sverre Alvik, vice president at the consultancy DNV. Households that buy a heat pump and fleets that order electric vans do not switch back when diesel gets cheaper. Carbon Brief reports governments signalling moves towards clean alternatives and away from imported liquefied natural gas.
Where Is the Change Already Structural?
India offers the comparison. Separate Carbon Brief analysis published on 16 September, by Lauri Myllyvirta and Anubha Aggarwal of the Centre for Research on Energy and Clean Air, finds India’s power sector emissions flat at 2024 levels for two years. It is the first two-year period in more than 50 years with no growth in Indian coal power.
Demand did not stall to achieve it. Total generation rose 7%, some 63TWh, equal to the annual consumption of Singapore or Switzerland. India added 77GW of solar, 11GW of wind, 5GW of hydro and 0.6GW of nuclear over the period. Clean supply absorbed the growth.
The same analysis records India’s overall emissions up 3.7% year on year in the first half of 2026, driven by steel and cement. Power is the solved part of the problem.
The Number to Keep in Mind
A 0.5% fall against 38.1 billion tonnes is roughly 190 million tonnes. It is real, and it is small. The test now is whether governments convert a supply shock into permanent demand reduction, or spend the peace restocking. India shows what the durable version looks like, and it was not built by a blockade.
Subscribe
Sign-up to receive our newsletter